Your Local Mortgage Lender
Located in Woodbridge & Dumfries, Virginia
Helping homebuyers and homeowners throughout Woodbridge, Dumfries, and Northern Virginia
find the right mortgage solutions with personalized guidance and expert advice.
Personalized Mortgage Experience
Markita Woods offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Mortgage Programs
Experience the best mortgage experience located in Woodbridge & Dumfries, Virginia.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
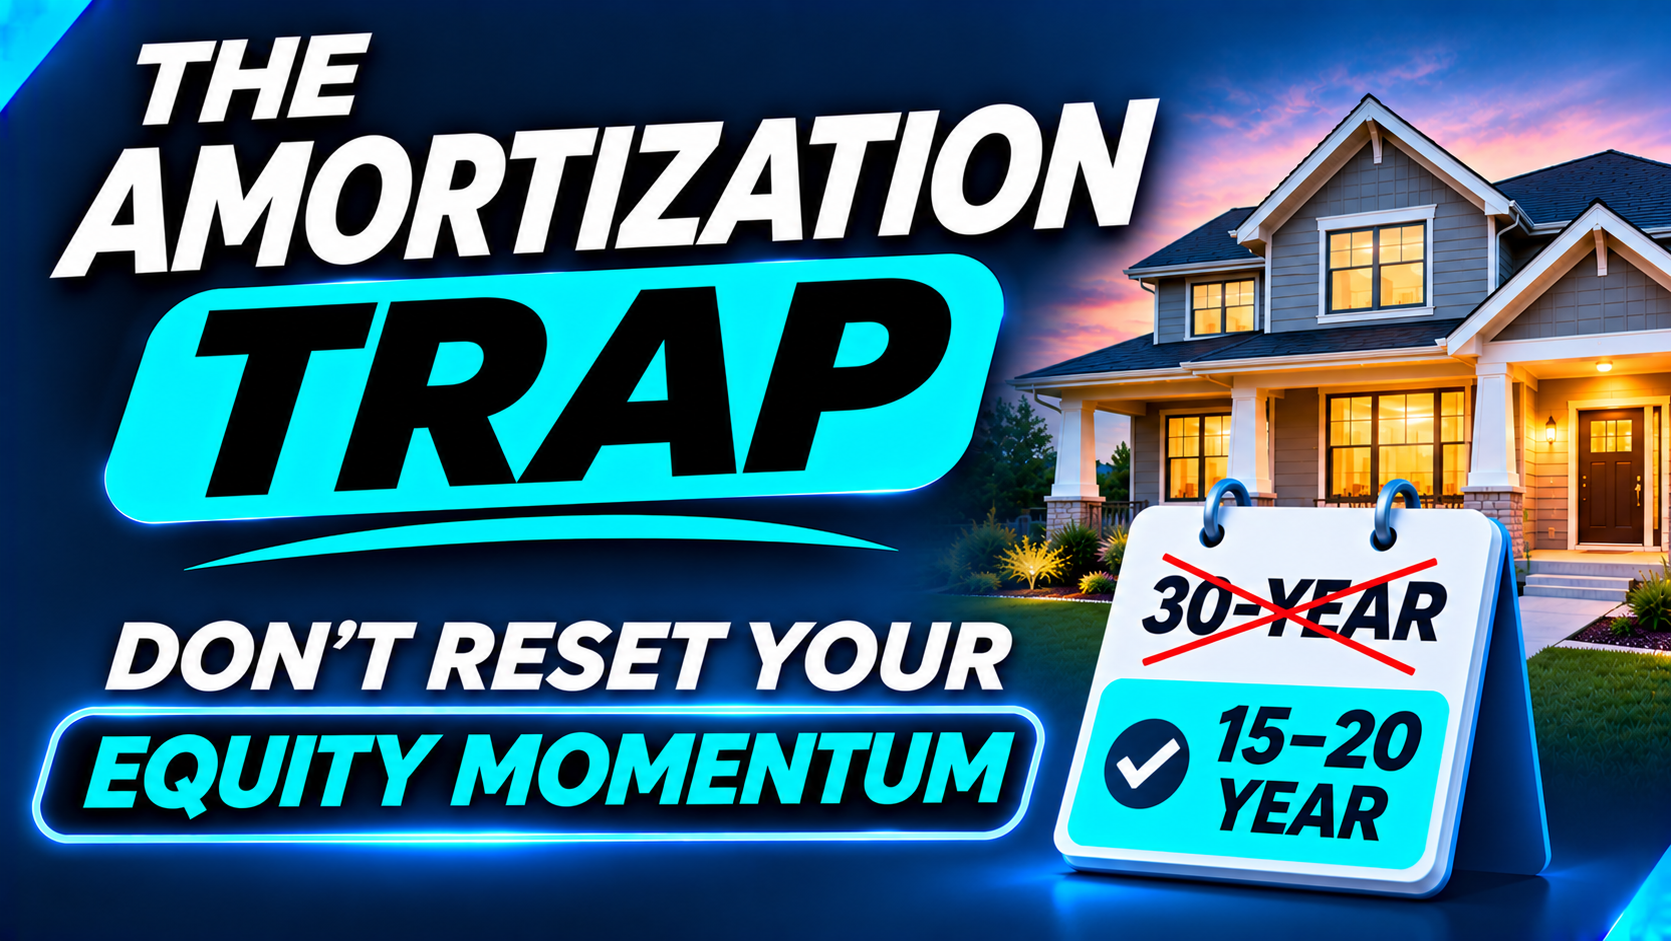
The Amortization Trap: Markita Woods on Refinancing Without Resetting Your Equity Progress
When a Refinance Quietly Sets You Back
Markita Woods warns about what she calls the amortization trap. If your goal is financial independence, refinancing into a brand new 30-year fixed mortgage might quietly set you back. A lower rate and a lower payment can look like a clear win, but the structure of the new loan can work against the progress you have already made.
Why Front-Loaded Interest Is the Problem
During the first several years of a standard mortgage, the bulk of every payment goes toward interest, barely touching your principal balance. That is how amortization works. Over time, the balance shifts, and more of each payment goes to principal. When you finally reach the phase where your equity begins accelerating, you are finally getting the benefit of all those early payments.
What a Fresh 30-Year Term Does
Jumping into a fresh 30-year term resets the amortization schedule back to day one. You are back in the stretch where most of your payment goes to interest. In effect, you give up your equity momentum in order to capture a lower rate. The savings may be real in the short term, but the cost shows up in slower principal reduction and potentially more total interest over the life of the loan. Whether a refinance makes sense depends on your rate, costs, and break even point, so the numbers matter.
A Smarter Equity Strategy
Markita explains that strategic wealth building means matching your refinance to a shorter term, such as 20, 23, or 15 years. Another option is to take a new 30-year loan but keep making your original payment, so the extra savings pays down principal directly. Either approach lets you capture a better rate without surrendering your progress. Payment flexibility and prepayment terms vary by loan, so confirm the details with your lender.
Protect Your Wealth
Financial independence is not just about shaving a few dollars off the monthly payment. It is about building equity that works for you over time. A lower payment helps cash flow, but the real goal is a structure that keeps your equity growing and moves you toward owning your home free and clear sooner.
Structure Financing That Keeps You on the Fast Track
If you are considering a refinance, reach out to Markita Woods and her team. They can help you structure financing that protects your equity momentum and keeps you on the faster track to freedom.
Sources
ConsumerFinancialProtectionBureau.gov
FreddieMac.com
Fanniemae.com
Bankrate.com
NerdWallet.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|