Your Local Mortgage Lender
Located in Woodbridge & Dumfries, Virginia
Helping homebuyers and homeowners throughout Woodbridge, Dumfries, and Northern Virginia
find the right mortgage solutions with personalized guidance and expert advice.
Personalized Mortgage Experience
Markita Woods offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Woodbridge & Dumfries, Virginia.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
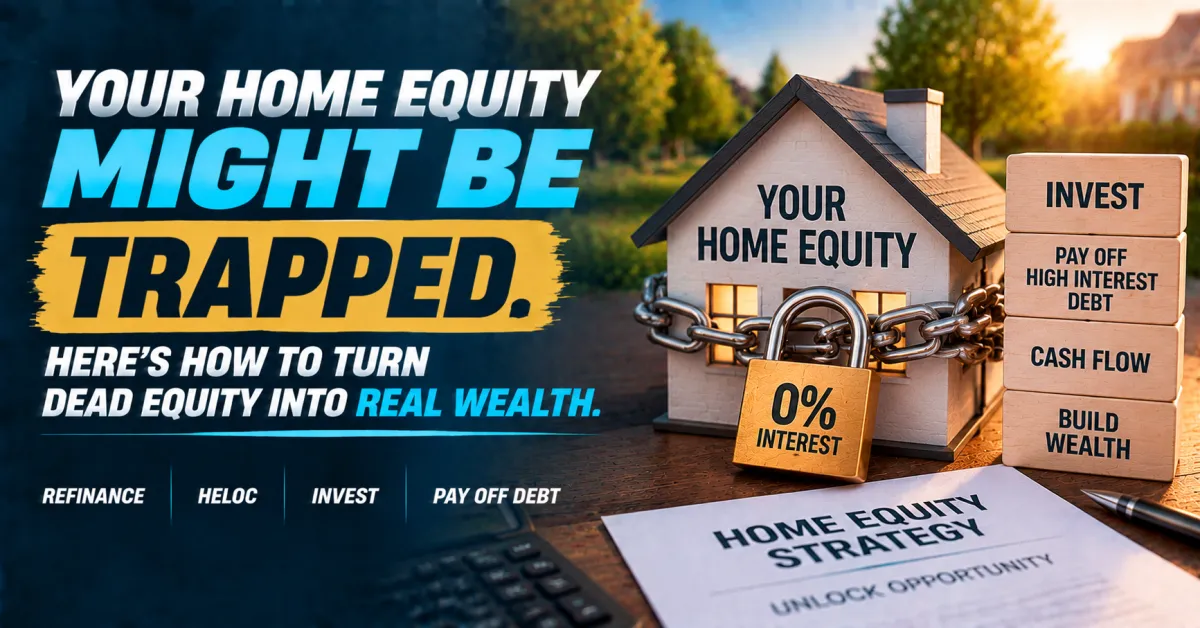
Dead Equity Is Wealth Sitting Idle in Your Walls and Here Is How to Put It to Work
Dead Equity Is Wealth Sitting Idle in Your Walls and Here Is How to Put It to Work
The Part of the Build Equity Message Nobody Tells You
Everyone tells you to build equity in your home. It is your biggest asset. It is the foundation of your financial future. All of that is true. But there is a part of the equity conversation that almost nobody has and Markita Woods the Queen of Mortgages wants to have it with you.
The money is completely trapped.
It is sitting in the walls. It is earning zero percent interest. And holding on to too much of it may actually be keeping you financially stuck rather than building the generational wealth you were told it would create.
What Dead Equity Actually Means
Consider two hundred thousand dollars in home equity. On paper you look wealthy. That number sits on your balance sheet and represents a meaningful asset. But you cannot buy groceries with it. You cannot invest with it. You cannot deploy it toward anything that generates a return. It is just there, appreciating at whatever the housing market does and doing nothing else.
That is dead equity. Wealth that is technically yours but practically inaccessible without taking deliberate action to unlock it.
Real lasting wealth requires money that is moving not sleeping. The difference between a two hundred thousand dollar equity position that sits idle and one that is strategically deployed into a cash flowing investment property or used to eliminate high-interest debt is the difference between looking wealthy and actually building wealth.
How to Safely Unlock Trapped Equity
Markita works with homeowners to unlock equity through two primary tools depending on the situation.
A strategic refinance accesses equity by replacing the existing mortgage with a new loan at a higher balance. The difference between the old balance and the new one comes to the homeowner as usable cash. When structured correctly the refinance can eliminate high-interest debt and redirect what were previously credit card minimum payments toward wealth-building activity instead.
A home equity line of credit provides flexible access to a defined credit line without replacing the existing mortgage. The homeowner draws what they need and pays interest only on what they use. The remaining credit line stays available for opportunities as they arise. For homeowners who want access without immediate deployment the HELOC preserves optionality while keeping the equity accessible rather than locked away.
What That Equity Can Do When It Is Working
High-interest debt elimination takes money that was flowing out to credit card companies at twenty to thirty percent annually and redirects it. The same dollars that were servicing expensive consumer debt become available for saving, investing, or building toward the next purchase.
Cash-flowing investment property acquisition uses the equity from a primary residence to fund the down payment on an income-producing asset. The equity that was sitting idle in one property becomes the foundation for a second property that generates monthly income and its own equity accumulation over time.
That is how dead equity becomes active leverage. That is how a homeowner's balance sheet stops being a static number and starts compounding.
What to Do Next
Send Markita Woods a message and she will build a clear step-by-step strategy for making your specific equity position work for you rather than sitting idle in your walls. Let's build generational wealth together.
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
Investopedia.com
BankRate.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

